MoonPay Applies for a National Trust Bank Charter, Joining the Crypto Charter Queue
MoonPay, the crypto payments company, has applied for a national trust bank charter, according to Decrypt. The goal is to expand its custody and stablecoin business under a federal banking license.
The firm is not alone. Decrypt reports that MoonPay joins a growing rush of crypto companies seeking federal trust charters, a trend that is now drawing more political scrutiny. The material available does not detail the regulator's timeline or any decision on the application.
A national trust charter is a type of federal license that lets a company hold assets for clients and offer related fiduciary services, without becoming a full-service bank that takes deposits and makes loans. For crypto firms, it is an appealing middle path: a stamp of federal legitimacy, and potentially less dependence on a patchwork of state-by-state approvals.
The custody and stablecoin focus makes sense. Safekeeping digital assets and issuing or handling dollar-pegged tokens are businesses where trust is the product. A federal charter is a way to tell customers and partners that someone in a suit is watching the vault.
The scrutiny is the catch. Traditional banking groups and some lawmakers have tended to question whether crypto firms should get access to the federal system on the same terms as established lenders. As more applications pile up, each new one becomes part of a larger political debate about how closely crypto and traditional finance should be intertwined.
For now, MoonPay's filing is an application, not an approval. Whether it ends up with a charter will say a lot about how open regulators are to letting crypto firms inside the banking tent.
Why it matters
Federal charters could give crypto firms more legitimacy and a clearer regulatory footing for custody and stablecoins, which matters for anyone who holds or spends digital assets. Political pushback shows the rules of the road are still being fought over.
Key points
- MoonPay applied for a national trust bank charter.
- The aim is to grow its custody and stablecoin business.
- It joins other crypto firms seeking charters amid growing political scrutiny.
Written by the PixelContent newsroom from public reports. Original reporting: Decrypt.
More stories
Bitcoin Slips Below $60K for First Time Since July as Stocks Sink
Bitcoin fell nearly 6% to below $60,000 for the first time since July as US stocks slid, with the Nasdaq down over 2% and Anthropic shares off almost 10%, Cointelegraph reported.
Bitcoin's Quantum Homework: Upgrading Could Take Longer Than Anyone Wants
Quantum computers can't break Bitcoin yet, but Leo Fan warns that upgrading the network and moving funds, including across bridges and custodians, could take longer than expected, CoinDesk reports.
Wrapped Monero token collapses 99.8% after suspected $13.5M exploit
A wrapped Monero token fell about 99.8% after a suspected exploit. Bitquery traced $13.5 million in suspicious sales, and the operator blamed a breach and promised to reimburse traders.
Senate Passes Bill to Ban Prediction Market Bets on War, Terrorism and Death
The Senate passed Sen. Adam Schiff's DEATH BETS Act, which would bar U.S.-regulated exchanges from listing prediction market contracts tied to war, assassinations or deaths, according to Decrypt.
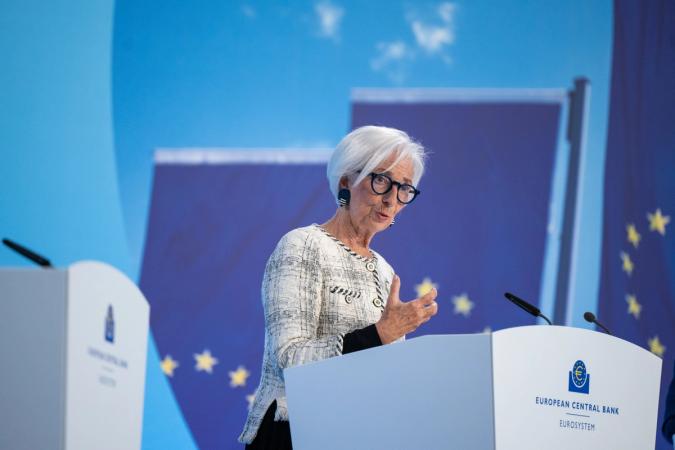
Lagarde Warns Europe Could Lose Grip on Tokenized Assets as a €1 Billion Digital Bond Settles
ECB President Christine Lagarde called for common EU rules on tokenized assets, warning Europe could lose control of the market, as a new blockchain settlement system processed a €1 billion digital bond.
Crypto's Daily Recap: The Market Never Sleeps, and Neither Do the Headlines
Cointelegraph ran its daily crypto roundup on Nov. 22, 2026, covering Bitcoin, DeFi, Web3 and regulation. The source material gave no specifics, so details are not available.